
A carat measures weight. It does not tell a reader which stones were sold, what buyers paid for comparable material or how much production remained in stock. Those distinctions are essential when a diamond output announcement becomes the starting point for a financial forecast.
On 18 December 2024, Reuters reported, citing Yakutia's regional government, that Alrosa's diamond output in Russia was down 4.6% to 33 million carats in 2024. That historical production figure is the anchor for this article. It is not a sales total, an inventory valuation or a measure of the price received for an unchanged assortment.
The following is an independent framework for interpreting volume and value, not an estimate of Alrosa's commercial results. Numerical examples use invented categories and prices. They do not represent actual diamond grades, quotations or company inventories. The purpose is to identify what additional evidence would be required before turning a physical production movement into a conclusion about revenue, demand or the value of unsold stock.
Start by identifying what crossed the measurement boundary
A production measure counts material entering an output category during a period. A sales measure counts material included in completed sales under the reporting definition. An inventory measure describes what remains at a date. These are connected, but they are not substitutes. A company can sell material produced earlier, retain part of current output or change the timing of a sale without changing the weight extracted during the period being discussed.
The first question is therefore not whether a percentage looks large or small. It is what the percentage measures. Does the denominator refer to the previous calendar year, the previous financial year or a comparable partial period? Does the scope include the same operations? Is the quantity rough material or a later processing stage? Answers should come from the relevant disclosure rather than assumptions attached to a familiar unit.
A careful reader should also preserve the date of the announcement. A report issued before a year has fully ended is evidence of what was reported at that time. It should not silently acquire the authority of a later audited reconciliation. If a subsequent publication uses a revised total, the difference needs explanation rather than a choice of whichever number best supports the desired argument.
Equal weight does not imply an equal commercial assortment
Weight is only one aspect of a diamond's description. The Gemological Institute of America explains polished diamond quality through colour, clarity, cut and carat weight. Its discussion concerns finished stones, not a ready-made method for pricing a miner's entire rough inventory. It supports the limited point that weight alone cannot establish commercial equivalence.
For a financial comparison, the practical issue is whether the items in one period can reasonably be compared with those in another. Two shipments can have the same total weight but different compositions. A change in the proportion of more valuable material can move the average realised price even if buyers pay exactly the same prices for comparable categories. Conversely, a less valuable assortment can reduce the average without proving that every comparable price fell.
That distinction is not unique to diamonds, but a weight-based headline makes it easy to overlook. The reader sees one number for quantity and one for value, divides them, and obtains a neat average. The calculation may be correct while the interpretation is wrong. An average price describes the particular goods sold; it does not automatically describe what happened to the price of an unchanged basket.
A fictional two-category example
Suppose an invented seller has two categories, called A and B solely for this example. Category A sells for 10 monetary units per carat and category B for 40. These figures are arbitrary and are not diamond quotations. In the first period the seller supplies 80 carats of A and 20 of B. Revenue is 800 plus 800, or 1,600, across 100 carats. The average is 16 monetary units per carat.
In the second period, the same seller supplies 50 carats of each category at unchanged category prices. Revenue is 500 plus 2,000, or 2,500, again across 100 carats. The average becomes 25. It has risen by 56.25%, even though neither category's price has changed. The increase comes entirely from the assortment sold. Calling it a general price increase would attribute the result to the wrong mechanism.
The example is deliberately simple. Real classification is more detailed, and not every item fits neatly into a stable category. Nevertheless, the lesson survives that complexity: before interpreting a unit-value movement, ask whether the weights of the categories changed. A sales average can be commercially useful without being a suitable price index. Keeping those uses separate prevents a correct division from becoming an unsupported market claim.
A fixed basket answers a different question
To isolate comparable price movement in the example, hold the basket at 80 carats of A and 20 of B, then revalue that same basket at each period's category prices. Since the prices did not change, its value remains 1,600. The fixed-basket comparison reports no price increase while the realised average rises sharply. Neither calculation is defective; they describe different things.
A company-level analysis might not have enough public detail to construct such a basket. That is a limitation to acknowledge, not an invitation to invent a classification. The responsible conclusion may be that the available average combines price and mix effects which cannot be separated from the disclosure. Stating that boundary is more informative than assigning the entire movement to one cause with unwarranted confidence.
Even a fixed basket needs review. If items in a category differ materially between periods, a category label may conceal a change rather than control for it. If a category disappears, the comparison requires a stated treatment. A transparent method explains these choices and retains the original definitions, allowing later readers to understand whether a change reflects the market, the sample or the method itself.
Production and sales need a physical reconciliation
Consider a separate invented inventory example. A business begins with 20 carats, produces 90 and sells 100, leaving 10, with no other movements assumed. Sales exceed production by 10 because opening stock supplies the difference. There is no contradiction. A reader looking only at production could miss the drawdown, while a reader looking only at sales could assume a level of current production that never occurred.
Reverse the situation and production can exceed sales while inventory grows. That does not by itself reveal why. The business may be preparing future assortments, responding to sale timing or facing weak demand. Each explanation needs evidence. The physical bridge establishes what changed; it does not establish the commercial reason. It is particularly important not to use an inventory increase as an automatic synonym for either confidence or distress.
- Record opening stock on the same physical basis as the period's additions.
- Separate new production from transfers or other additions where the disclosure does so.
- Identify the quantity included in sales and any other removals.
- Reconcile the result with closing stock before explaining the movement.
- Keep unresolved differences visible rather than assigning them to a convenient narrative.
In actual reporting, classifications and other movements may make the bridge more complicated than the example. The correct response is to inspect the definitions, not to force every residual into sales. Physical reconciliation is a discipline of scope. Once quantities are aligned, value can be analysed with less risk of confusing a change in stock with a change in the price paid for it.
The sold assortment can differ from the remaining stock
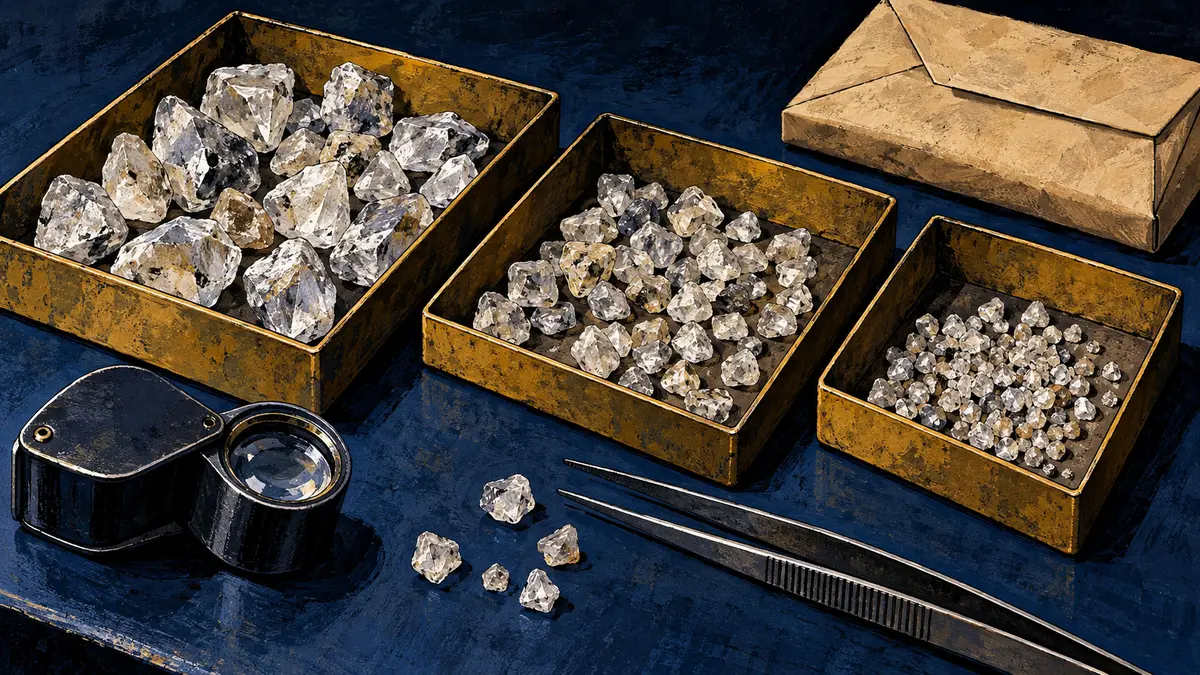
An especially important error is to apply the average price of recent sales to every unsold carat. That assumes the remaining stock has the same composition and can be sold on equivalent terms. If the sold assortment was selected differently, the assumption fails. A high realised average may coexist with a less valuable residual stock, or the reverse. The direction cannot be inferred from the average alone.
A useful inventory discussion therefore asks what evidence connects the remaining material to the sales used as comparators. Are the categories comparable? Are the observation dates relevant? Do the transactions represent ordinary sales or an unusual package? These are questions about evidence, not an attempt to value individual stones from a public headline. A defensible answer may require information that outside readers do not possess.
This also matters when comparing two producers. Similar total carats do not establish similar revenue potential, cost structure or market exposure. The operations may produce different assortments and sell through different arrangements. A ranking by weight is a ranking by weight. Extending it into a ranking of financial strength requires additional measures and a consistent basis, rather than treating the largest physical total as a universal indicator of commercial advantage.
Do not combine rough and polished stages
The material sold by a miner and the finished item offered to a jewellery customer occupy different stages of a chain. A retail quotation cannot simply be multiplied by rough output. Processing, selection and selling activities stand between those observations, and the units being compared may not retain the same weight or characteristics. The error is one of boundary before it is one of arithmetic.
A model should specify its stage explicitly. If it concerns rough sales, it needs comparable rough transactions. If it concerns a processing operation, it needs the relevant input, output and cost assumptions. If it concerns a finished product, it needs evidence for that product's market. Combining the highest visible selling price with the earliest physical production total can create an attractive but meaningless estimate.
For the same reason, an illustrative yield should never be smuggled into a company forecast. A generic assumed conversion factor is not evidence about a particular parcel or production mix. Where the required data are absent, the model can remain a sensitivity exercise with its assumptions clearly marked. It should not be presented as a recovered fact about a business whose actual conversion economics have not been observed.
Separate operating explanations before building a forecast
A fall in output can reflect several possible operational choices or constraints. Without supporting evidence, it cannot be labelled automatically as a deliberate response to price, a resource problem or a sign of weaker customer demand. Those explanations lead to different expectations about future production. The headline quantity alone does not choose between them, even when one explanation seems plausible in the wider market narrative.
Likewise, an increase in revenue need not imply more physical production. It can be consistent with a different sales assortment, different prices, stock drawdown or a combination. The analytical task is to separate these possibilities as far as the evidence permits. A forecast that places all change into one convenient variable may fit the last reported total while misunderstanding the mechanism that produced it.
One practical approach is to build separate quantity, mix and comparable-price scenarios. Each should show which assumptions are supported and which are illustrative. Changing one variable at a time first makes the sensitivity intelligible. Combined scenarios can follow, but their additional complexity should not obscure the fact that several uncertain inputs are moving together. A detailed spreadsheet does not reduce uncertainty merely by containing more cells.
Use uncertainty to define the next useful question
The absence of a full public breakdown does not make analysis pointless. It changes the appropriate output. Rather than announcing a precise valuation, an analyst can identify the disclosure that would resolve the largest ambiguity: a sales quantity, a consistent category breakdown, an inventory movement or an explanation of a changed reporting boundary. That is a concrete research result, even if it leaves a financial estimate as a range.
Questions should also be ranked by importance. If sales weight is unknown, elaborate adjustments to an assumed price may add little value. If sales weight is known but the assortment changed, the priority shifts to mix. If comparable prices are available but stock composition is not, applying them to inventory remains uncertain. The sequence prevents attention from drifting toward the most accessible number rather than the most consequential missing fact.
The historical output announcement should therefore retain a precise role. It tells the reader something about reported physical production at that time. It does not fill every gap between extraction and commercial value. Treating that boundary seriously is not pessimism about the industry or optimism about an individual company. It is simply the difference between measuring what is known and assigning meaning that the evidence has not earned.
A strong reading of diamond results begins with the unit, follows the material through production and sales, and checks the assortment behind the average. It keeps a fixed-basket price comparison distinct from a realised unit value and resists valuing unsold stock with an unrelated sales mix. Only then can a change in carats contribute to a financial explanation. Weight is the starting observation; commercial equivalence is the question that makes it useful.