
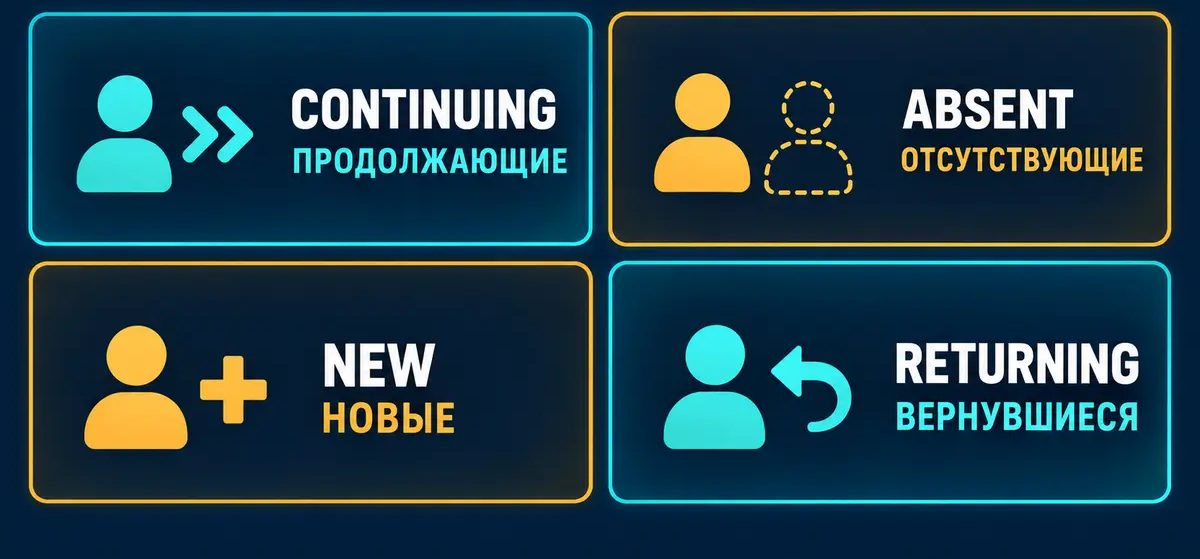
A customer can disappear from a quarterly paying population without disappearing from the business relationship. Another can enter the count for the first time while contributing little revenue. Between those two movements, an average can rise even when the accounts present in both periods spend exactly the same amount. Understanding the change requires following identities, not merely comparing two totals.
On 14 November 2025, Interfax reported that HeadHunter's small and medium-sized business payer count fell 19.3% in the third quarter while average revenue per client rose 11.5%. The company attributed much of the average's growth to the departure of new, low-consumption clients. That attributed explanation from Russia provides a narrow starting point, not a complete description of customer retention.
The analysis below develops an independent, fictional account-reconciliation exercise. It does not reproduce the company's metric definitions, estimate its churn or infer the prices its customers paid. Its purpose is to show how a business can distinguish customers who continue buying, customers absent from a particular period, genuinely new customers and customers returning after an interruption. Those distinctions support different operating decisions.
Give the population a name before counting it
A useful customer measure begins with an admission rule. Does the count include an account that bought something during the period, an organisation with an active contract, or an organisation that used a service? Each rule describes a different population. Without the definition, the word customer appears more precise than the underlying observation. A reader should not silently replace a reported paying population with all organisations that maintain a relationship.
For the exercise here, a payer is a distinct account making a purchase within one specified period. The example assumes that the purchase amount is also the revenue attributed to that account in the same period, with no timing differences. This simplifying assumption is not a statement about actual accounting. In a real reconciliation, purchases, cash receipts and recognised revenue may require separate fields and separate dates.
The identity rule matters just as much as the admission rule. If one organisation opens a second account, the system may record two identifiers but only one commercial relationship. If two organisations merge, a surviving identifier may conceal a changed reporting perimeter. An analyst needs an explicit treatment of these cases before labelling a movement acquisition, loss or expansion. Otherwise administrative changes can acquire a commercial meaning they do not possess.
Build the matched account list
Start with two lists constructed using the same period length and the same admission rule. Match the identifiers before calculating growth. Some accounts appear on both lists; others appear only on the first or only on the second. This simple operation turns an anonymous change in population into a set of movements that can be investigated. It does not yet explain why the movements occurred.
The accounts present in both periods form the continuing group. Their spending can be compared on an identified basis. Accounts present only in the first period are absent payers in the second. That is an observation, not a diagnosis. Accounts present only in the second require a search further back: they might be genuinely new to the service or returning after an earlier purchase outside the comparison window.
Preserve unmatched records rather than forcing them into a convenient group. A changed identifier, missing transaction or account consolidation may need resolution. The reconciliation should show how many records remain uncertain and whether they could materially alter the conclusion. A neatly balanced table is not useful if it achieves balance by treating every unresolved account as a lost customer or every newly issued identifier as an acquisition.
Follow the same fictional accounts through two periods
Consider an invented service with 100 paying accounts in its first period. Eighty accounts each spend 10 monetary units, contributing 800 in total. Twenty other accounts each spend 2 units, contributing another 40. Total revenue under the exercise's simplified rule is 840, and the average across the 100 payers is 8.4. These are arbitrary amounts, not prices or customer segments observed at a real company.
In the second period, the same 80 continuing accounts still spend 10 units each. Their contribution remains 800. The other 20 first-period accounts make no purchase during the second period. Five genuinely new accounts each spend 2 units, adding 10. The second list therefore contains 85 payers and revenue of 810. The accounts have been followed individually; none has been inferred from the movement in the average.
The average becomes approximately 9.53, an increase of about 13.45%, while total revenue falls about 3.57%. Yet spending by every continuing account is unchanged. The important result is not the rising average itself. It is the ability to point to the exact sources of the revenue movement: 40 from first-period accounts is absent and 10 arrives from new accounts. No increase within the continuing group fills the difference.
The revenue bridge has a separate job
Write the bridge as opening revenue of 840, plus zero change from continuing accounts, minus 40 associated with absent accounts, plus 10 from genuinely new accounts, giving closing revenue of 810. Every amount has an identified population behind it. The bridge explains the arithmetic without pretending to explain the motives of the twenty accounts that did not buy again during this window.
A comparison restricted to continuing accounts is 800 against 800, or 100% of their previous spending. That is a deliberately defined comparison within this exercise. It should not be renamed a published net revenue retention measure, because a different measure may retain departed customers in its original cohort or apply other rules. Similar-looking percentages can answer different questions when their populations differ.
Keep absent accounts in the investigation
Removing absent accounts from the current paying average does not remove them from the commercial question. The business may want to know whether they stopped needing the service, moved to another supplier, delayed a purchase or simply buy infrequently. The two-period transaction lists cannot choose among those explanations. Account history and appropriately obtained customer feedback can help, but uncertainty should remain visible where evidence is incomplete.
Suppose five of those absent accounts purchase again in a later period. If their identities are retained, the business can describe them as returning accounts. If their earlier history has been discarded, the same activity may be celebrated as new acquisition. That error changes the apparent performance of marketing and account management even though the underlying purchases are identical. A longer history improves classification without guaranteeing a permanent relationship.
The lookback window should therefore be stated. An account can be new to the current comparison and old to the business. Equally, a period without payment is not necessarily a terminated contract. The suitable observation window depends on the question being asked and the buying pattern being investigated. There is no universal number of quiet months that turns every service relationship into a confirmed loss.
Separate acquisition work from continuing-account work
The fictional bridge creates at least two operating questions. Why did the first-period low-spending accounts not purchase during the second window? And what happened to genuinely new demand? Those questions may involve different teams, evidence and remedies. A single average cannot tell management whether to change acquisition activity, contact dormant accounts or investigate the experience of established buyers.
Nor does a small initial purchase automatically mean that a customer is unattractive. It may be a limited trial, an occasional need or the beginning of a longer relationship. Evaluating acquisition requires costs and subsequent outcomes, not simply ranking customers by their first-period spending. The fictional model contains no servicing costs, margins or later lifetime value, so it cannot identify which accounts the business should prefer.
Continuing-account spending also deserves a closer view. In the example it is unchanged for every account by construction. In an actual dataset, an unchanged total could conceal expansion at some accounts and contraction at others. An identified bridge can preserve both movements instead of netting them immediately. That gives account teams a more useful starting point while avoiding a claim that any particular real company's customers behaved this way.
Do not turn a payer count into a hiring count
A recruitment-related purchase and a hiring outcome occupy different stages of a process. An organisation can make one purchase to support several searches, buy again without completing a hire, or fill a position through another route. Those possibilities show why a payer count cannot be translated mechanically into employees recruited. The missing relationship has to be measured, not supplied by intuition.
The same restraint applies to demand across the wider economy. A change in one platform's paying population may reflect factors specific to its service, customer base or observation period. It does not by itself establish the number of employers seeking staff everywhere. The correct scope of the conclusion is the scope of the evidence. A narrow account reconciliation can be useful without pretending to represent an entire labour market.
For an operating review, distinguish the questions explicitly: who bought, what service was purchased, what activity followed, and what outcome can actually be observed? Linking these stages may require different records and permissions. Where the linkage is unavailable, report the gap. Filling it with an assumed conversion rate would produce a precise-looking answer with no stronger factual foundation.
Check the records before judging the teams
A reconciliation can affect how an organisation evaluates acquisition, retention and customer service. That makes record quality a management issue rather than a clerical detail. If account merges are credited as expansion, or returning accounts as new wins, incentives can reward classification changes rather than better performance. Consistent rules should be fixed before the result is used to allocate credit.
- Keep one declared account-identity rule across both periods.
- Record the observation window and the event that qualifies an account as a payer.
- Separate continuing, absent, genuinely new and returning accounts.
- Retain a visible category for unresolved identity changes.
- Reconcile account-level amounts to the same revenue perimeter.
- Document corrections without rewriting the earlier interpretation silently.
This checklist is not a demand to publish identifiable customer records. The internal matching can support an aggregated explanation that protects confidential information. What matters to the reader is whether the categories are consistent and the totals reconcile. A business can explain the mechanism of a change without exposing the names, transactions or employment plans of individual customers.
Review a sample of classifications before relying on the whole table. An account described as new might have an older identifier; an absent account might have moved into a consolidated buyer. Finding such cases does not invalidate cohort analysis. It identifies where the mapping needs repair and where an apparently commercial change is actually a record-keeping event.
Make a correction reproducible
Imagine that a reviewer discovers that one supposed new account is a returning buyer whose earlier identifier changed. The correct response is to repair the classification and retain an explanation of the change. Total revenue may remain untouched while the acquisition narrative changes. This is precisely why a review should store the rule used for matching, the relevant observation dates and a record of exceptions, rather than only the final aggregate percentages.
Another reviewer should be able to repeat the classification from the same permitted records and obtain the same groups. If the answer depends on an undocumented judgement by the original analyst, the method is fragile. Some cases genuinely require judgement, but the decision and its reason can still be recorded. A reproducible process does not eliminate ambiguity; it makes the treatment of ambiguity inspectable and allows later evidence to improve the result.
For the fictional exercise, no such corrections are needed: the identities are fixed by assumption. In an operational setting, however, a corrected history can change which team appears to have gained or recovered an account. That is a reason to distinguish provisional classifications from reviewed ones. It is not a reason to delay every useful analysis indefinitely or to disguise uncertain records inside a confidently named category.
Use the bridge to choose the next question
The fictional result does not justify a general verdict about the health of a service. It shows a specific revenue gap and the populations associated with it. That is enough to make the next investigation more focused. The business can examine the absent group, assess the genuinely new group and review continuing accounts separately instead of treating a higher average as a complete explanation.
Even a clean bridge remains descriptive. To argue that a particular campaign, price decision or product change caused a movement, the analyst needs additional evidence. Timing alone is not sufficient: customers may respond to several changes at once. A responsible account review distinguishes an observed classification, a plausible explanation and a tested conclusion rather than presenting all three with equal confidence.
The strongest use of the exercise is therefore practical and limited. Preserve customer identities, define the paying population, reconcile the amounts and keep temporary absence distinct from confirmed departure. Once those steps are complete, the average becomes one summary among several. The question that matters is no longer merely whether revenue per payer rose, but which relationships continued, which paused, which began and what evidence supports the explanation.